
Understanding bonds
Bonds promise steady income – but defaults do happen. Understand how bond pricing, yields, and credit ratings work in Singapore before adding fixed income to your portfolio.
Last updated on 14 October 2026
Key takeaways
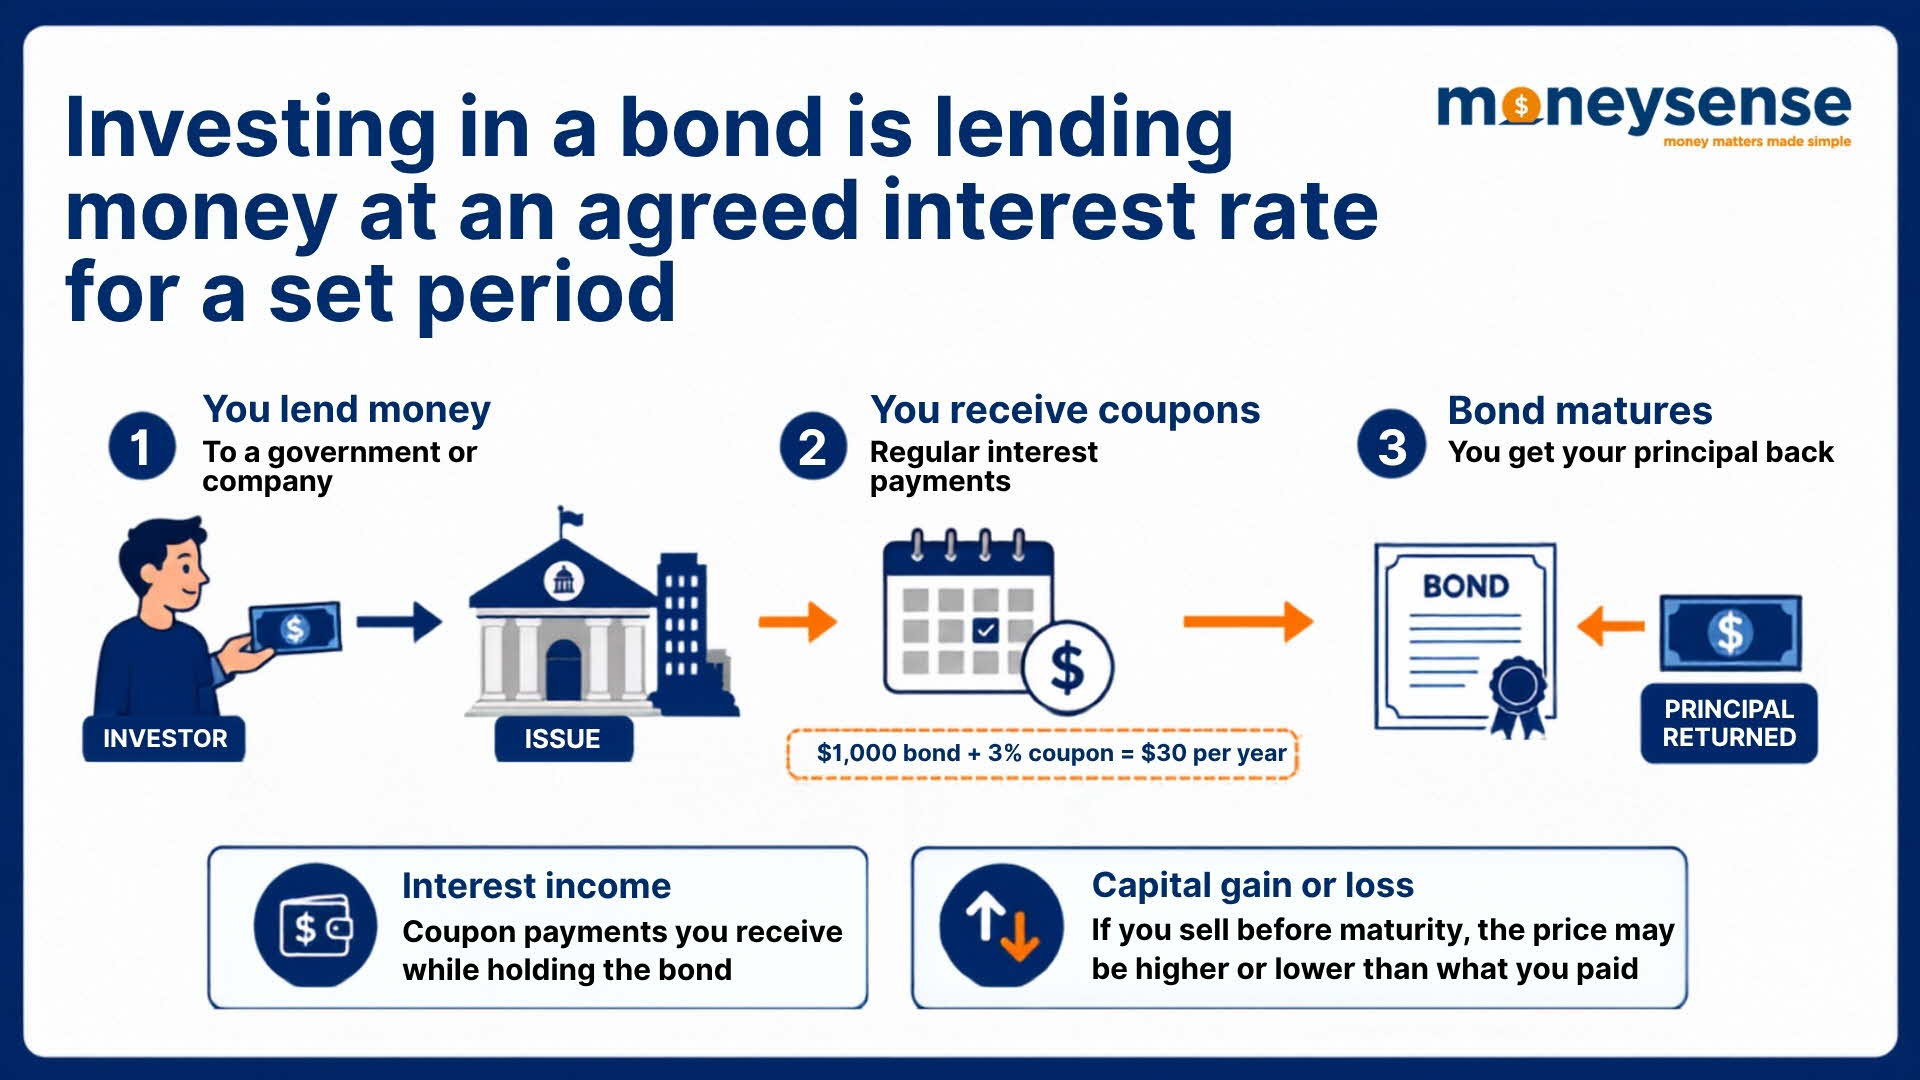
When you invest in a bond, you are lending money to a government or company at an agreed interest rate for a fixed period.
Bondholders receive regular interest payments (called a “coupon”) and are repaid the principal when the bond matures — provided the issuer does not default.
Bond prices and interest rates move in opposite directions: When rates rise, bond prices typically fall, and vice versa.
Not all bonds are low-risk. Non-investment grade (“junk”) bonds can be riskier than some shares. Always check credit quality before investing.
How bonds work
A bond is a debt security — in plain terms, an IOU. You lend money to the issuer (a government or company), and in return they promise to pay you regular interest and return your principal at the end of the agreed term (called the maturity date).
Most bonds pay a regular stream of income called a coupon. Coupon rates are expressed as a percentage of the bond’s face value (also called par value). For example, a bond with a face value of $1,000 and a 3% per annum coupon pays you $30 per year.
Your total return from a bond combines:
Interest income: The coupon payments you receive while holding the bond.
Capital gain or loss: If you sell before maturity, the price you receive may be higher or lower than what you paid. If you hold to maturity and the issuer does not default, you receive your principal back regardless of how prices moved in between.
Why bond prices change
While the coupon rate on most bonds is fixed at issuance, the market price of the bond changes constantly. The most important driver is interest rates:
When prevailing interest rates rise: Newly-issued bonds offer higher coupons, making existing lower-coupon bonds less attractive, so their prices fall.
When interest rates fall: Existing higher-coupon bonds become more attractive relative to new issues, so their prices rise.
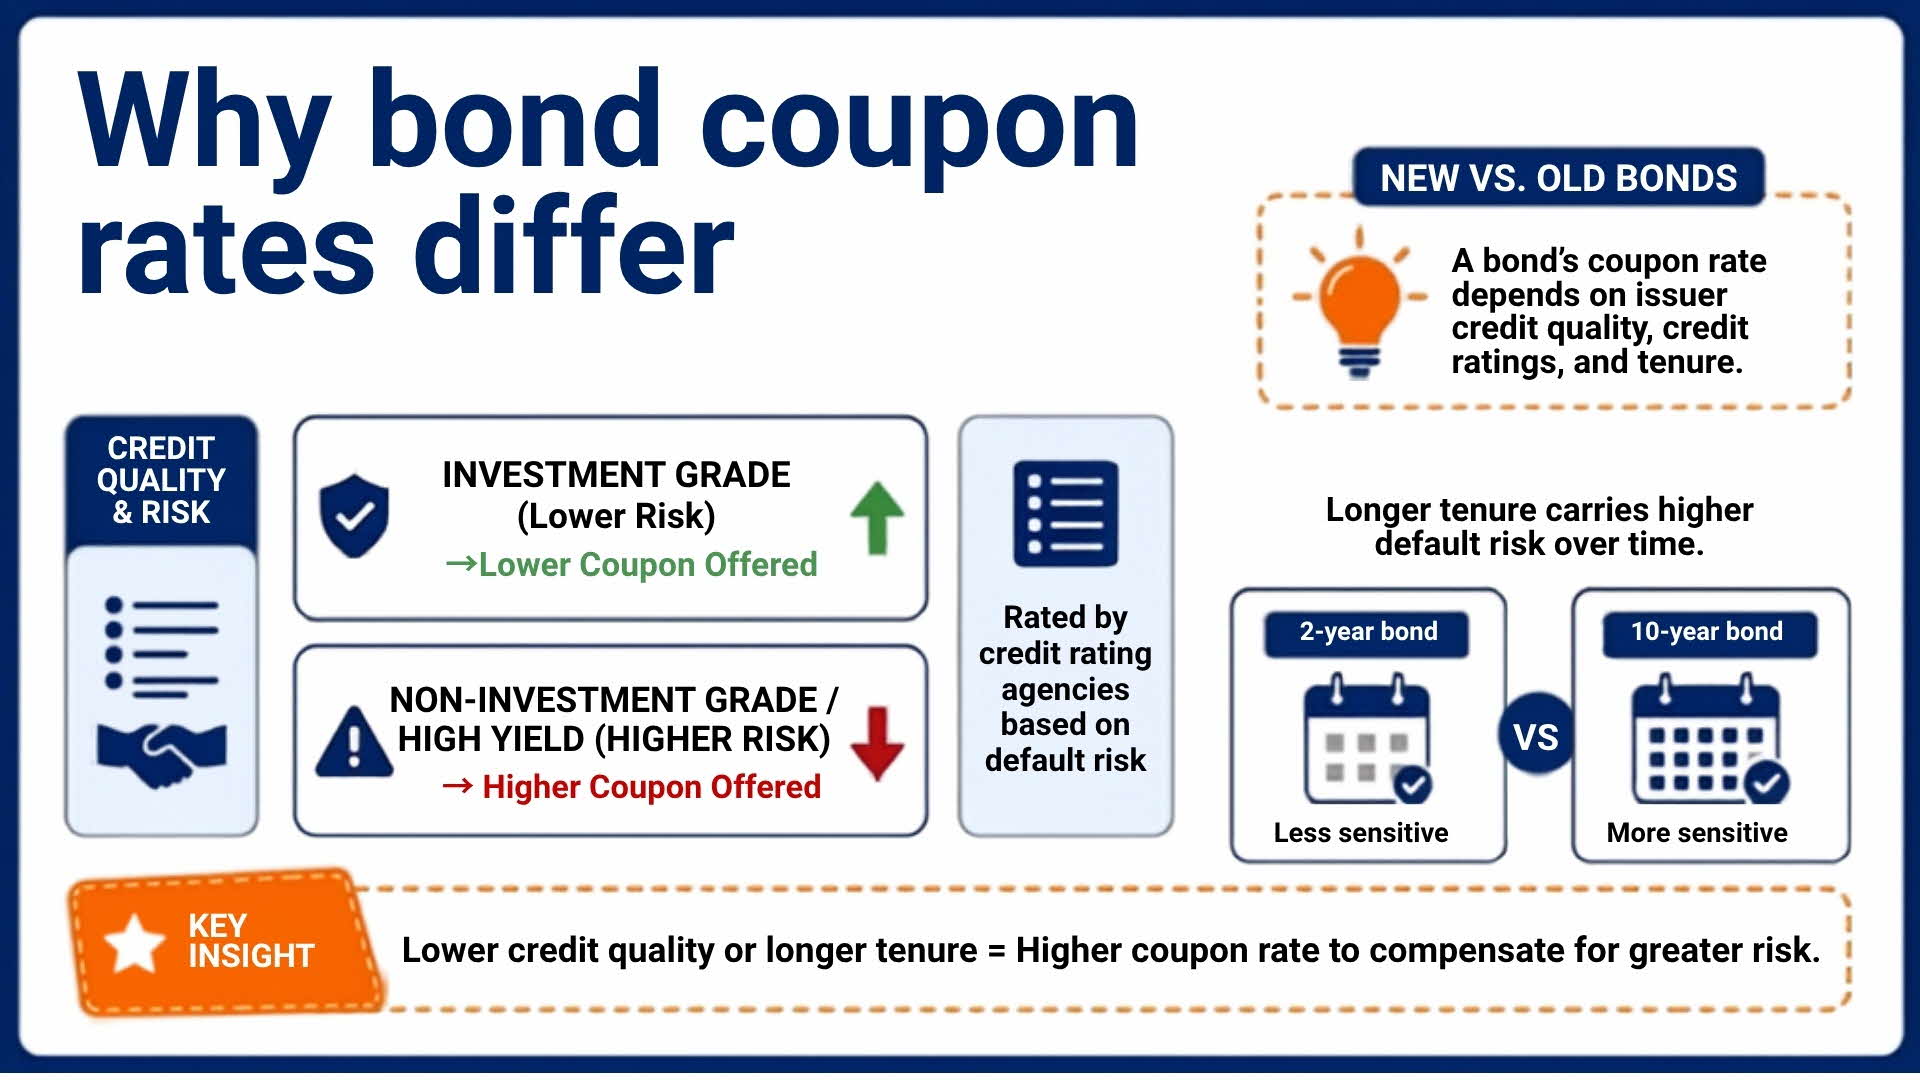
Key insight: Longer-dated bonds are more sensitive to interest rate changes than short-dated bonds. The same 1% rate rise will cause a 10-year bond to fall more in price than a 2-year bond.
Credit quality and credit ratings
Not all bonds carry the same risk. The probability of an issuer failing to pay you back is called credit risk. Issuers with weaker financial health pay higher coupon rates to compensate investors for taking on more risk.
Independent rating agencies — Moody’s, Standard & Poor’s (S&P), and Fitch — assign credit ratings to bonds and issuers:
Examples of credit ratings from independent agencies
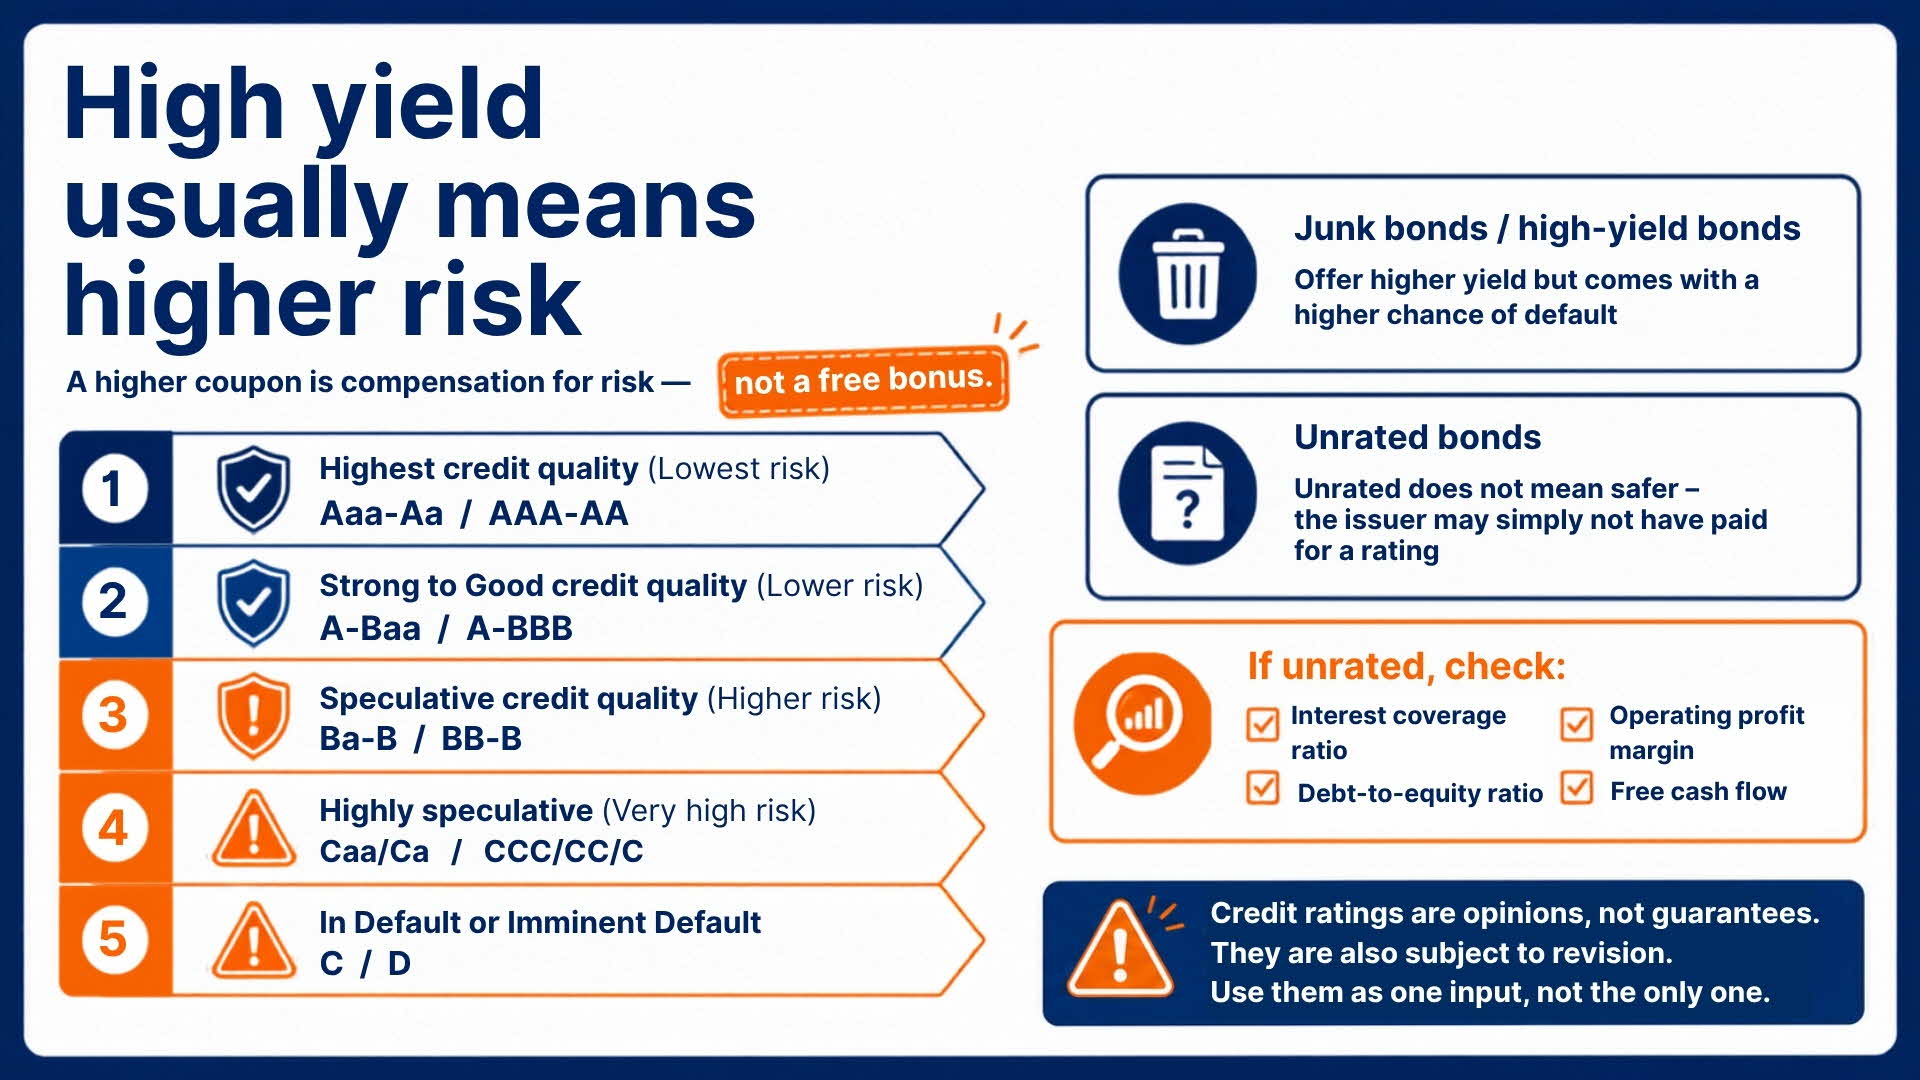
Moody’s | S&P / Fitch | Grade and quality |
Aaa – Aa | AAA – AA | Investment grade – High |
A – Baa | A – BBB | Investment grade – Medium |
Ba – B | BB – B | Non-investment grade – Speculative |
Caa/Ca | CCC/CC/C | Non-investment grade – Highly speculative |
C | D | Non-investment grade – In default |
Non-investment grade bonds are also called “junk bonds” or “high-yield bonds”. The higher yield compensates for a meaningfully higher chance of default. Do not treat a high yield as a reward without risk; it signals higher risk.
Some bonds carry no credit rating. An unrated bond is not necessarily safer than a rated one — it may simply mean the issuer chose not to pay for a rating. For unrated bonds, assess the issuer’s creditworthiness using their financial statements.
Useful metrics include:
Interest coverage ratio | How many times the issuer can cover its annual interest payments with its operating income. A ratio below 1 means the issuer does not earn enough to cover its interest — a serious warning sign. |
Debt-to-equity ratio | How much debt the issuer has relative to its equity. A ratio above 2 means the issuer has more than twice as much debt as equity, suggesting higher financial risk. |
Operating profit margin | The share of revenues left after paying operating expenses. A declining margin suggests a growing risk that the issuer cannot service its fixed obligations. |
Free cash flow | The cash generated after maintaining assets. Consistently positive free cash flow indicates a financially healthy issuer. |
Note on ratings: Credit ratings are opinions, not guarantees. They are based on information available at the time of assignment and can be revised or withdrawn. An issuer’s financial position can change faster than a rating agency updates its view. Use ratings as one input, not the only one.
Types of bonds available in Singapore
Singapore Savings Bonds (SSBs) and Singapore Government Securities (SGS)
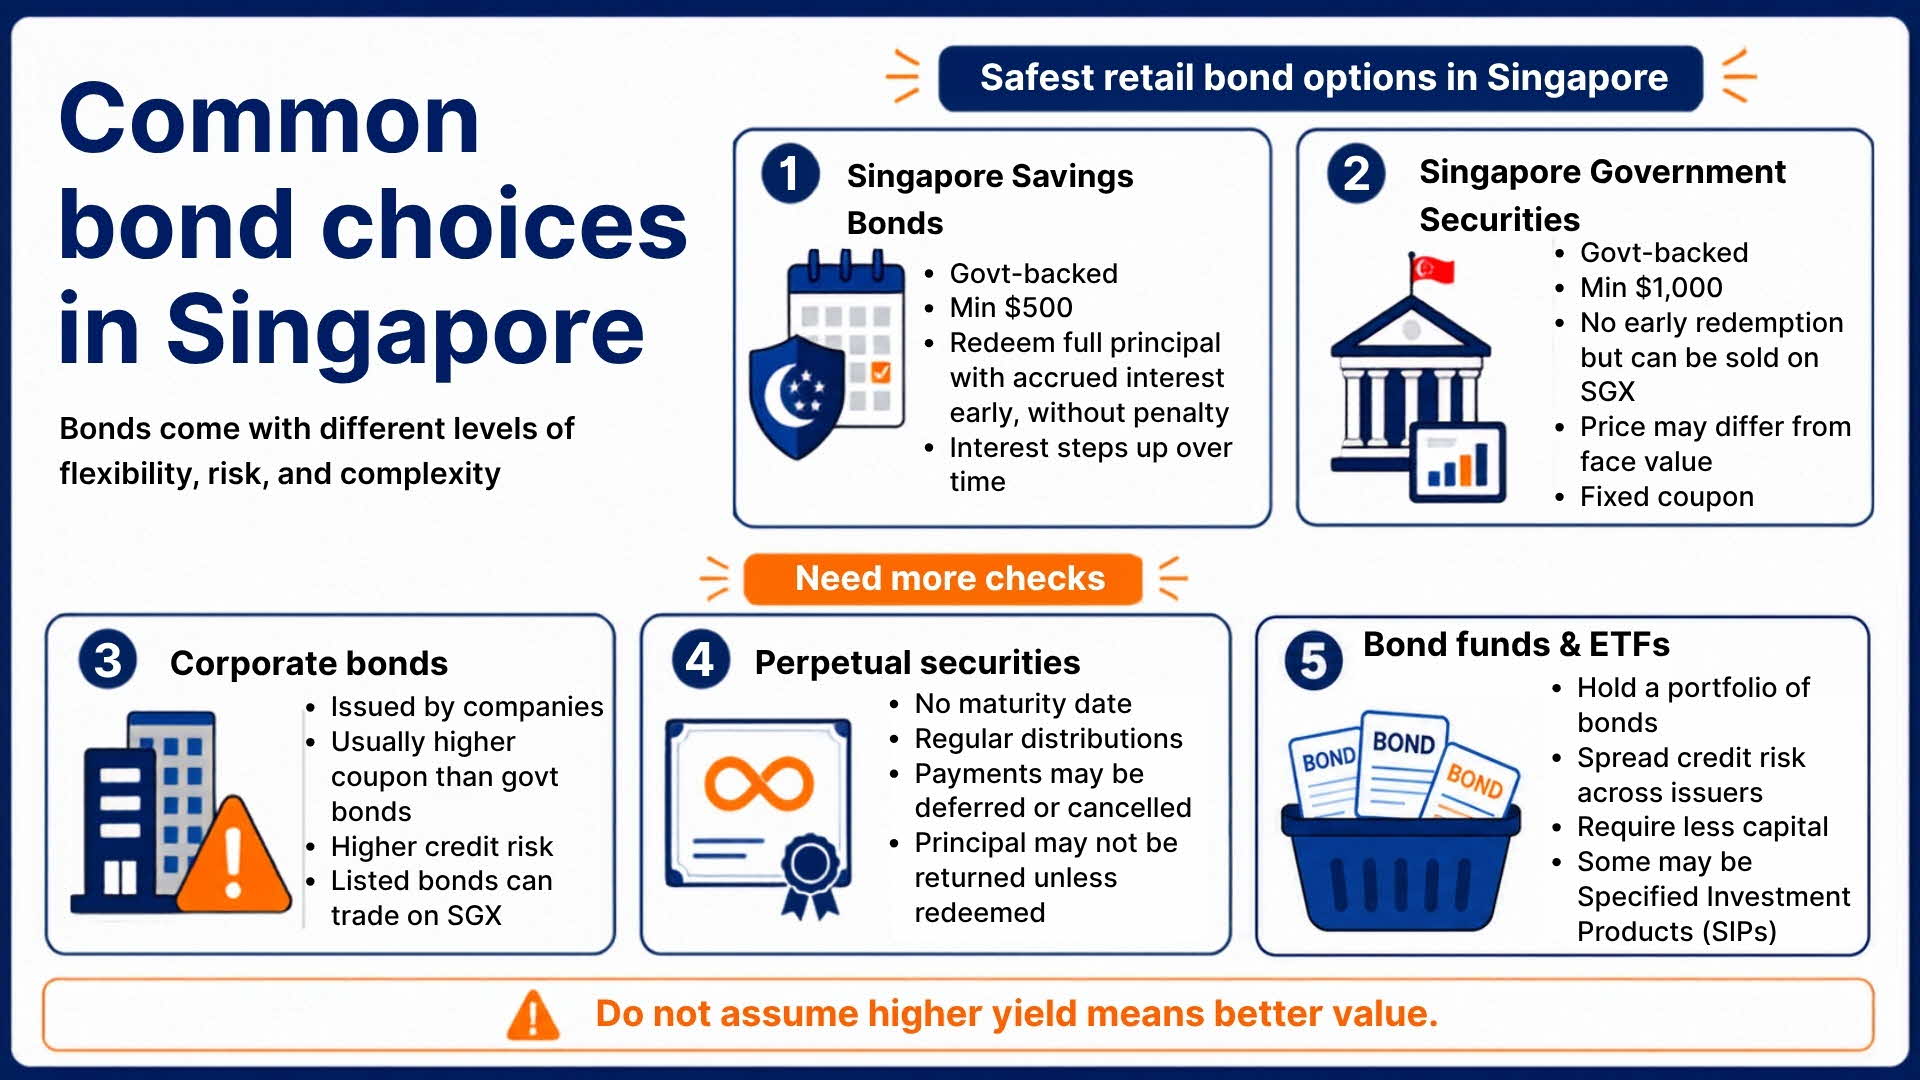
Both are backed by the Singapore Government and considered risk-free within Singapore. They are the safest bonds available to retail investors here.
Singapore Savings Bonds (SSBs) and Singapore Government Securities (SGS)
SSBs | SGS |
Designed specifically for individual investors | Available to retail and institutional investors |
Not tradable on the exchange | Can be sold on the SGX secondary market before maturity (price may differ from face value) |
Flexible: redeem early in any month without penalty, receiving principal plus accrued interest | No early redemption; must be sold on secondary market if you need funds before maturity |
Interest steps up over time — the longer you hold, the higher your average yield | Fixed coupon rate for the full term |
Minimum investment: $500; maximum holding per person: $200,000 | Minimum investment: $1,000; no holding limit |
How to invest in SSBs: Apply via internet banking or ATMs of the three local banks. Check current rates and application windows at MAS’ website. (opens in new tab)
Corporate bonds
Issued by companies, corporate bonds generally pay higher coupon rates than government bonds to compensate for greater credit risk. Listed corporate bonds on the Singapore Exchange (SGX) can be bought and sold the same way as shares.
Do not assume higher yield means better value. Higher yield reflects a higher probability that something goes wrong. Always assess the issuer’s credit quality before committing.
Perpetual securities
Perpetual securities (“perps”) are hybrid instruments with no maturity date. They pay regular distributions, but the issuer typically has the discretion to defer or cancel payments in certain circumstances. The lack of a maturity date also means you may not get your principal back unless the issuer chooses to redeem. Read the terms carefully.
Bond funds and ETFs
Rather than buying individual bonds, you can gain diversified bond exposure through unit trusts or Exchange-Traded Funds (ETFs) that hold a portfolio of bonds. This spreads your credit risk across many issuers and requires less capital. Note that some bond ETFs are classified as Specified Investment Products (SIPs) and require a knowledge assessment before purchase. See the Guide to ETFs for more on SIPs and their requirements.
Key risks in bond investing
Key risks in bond investing
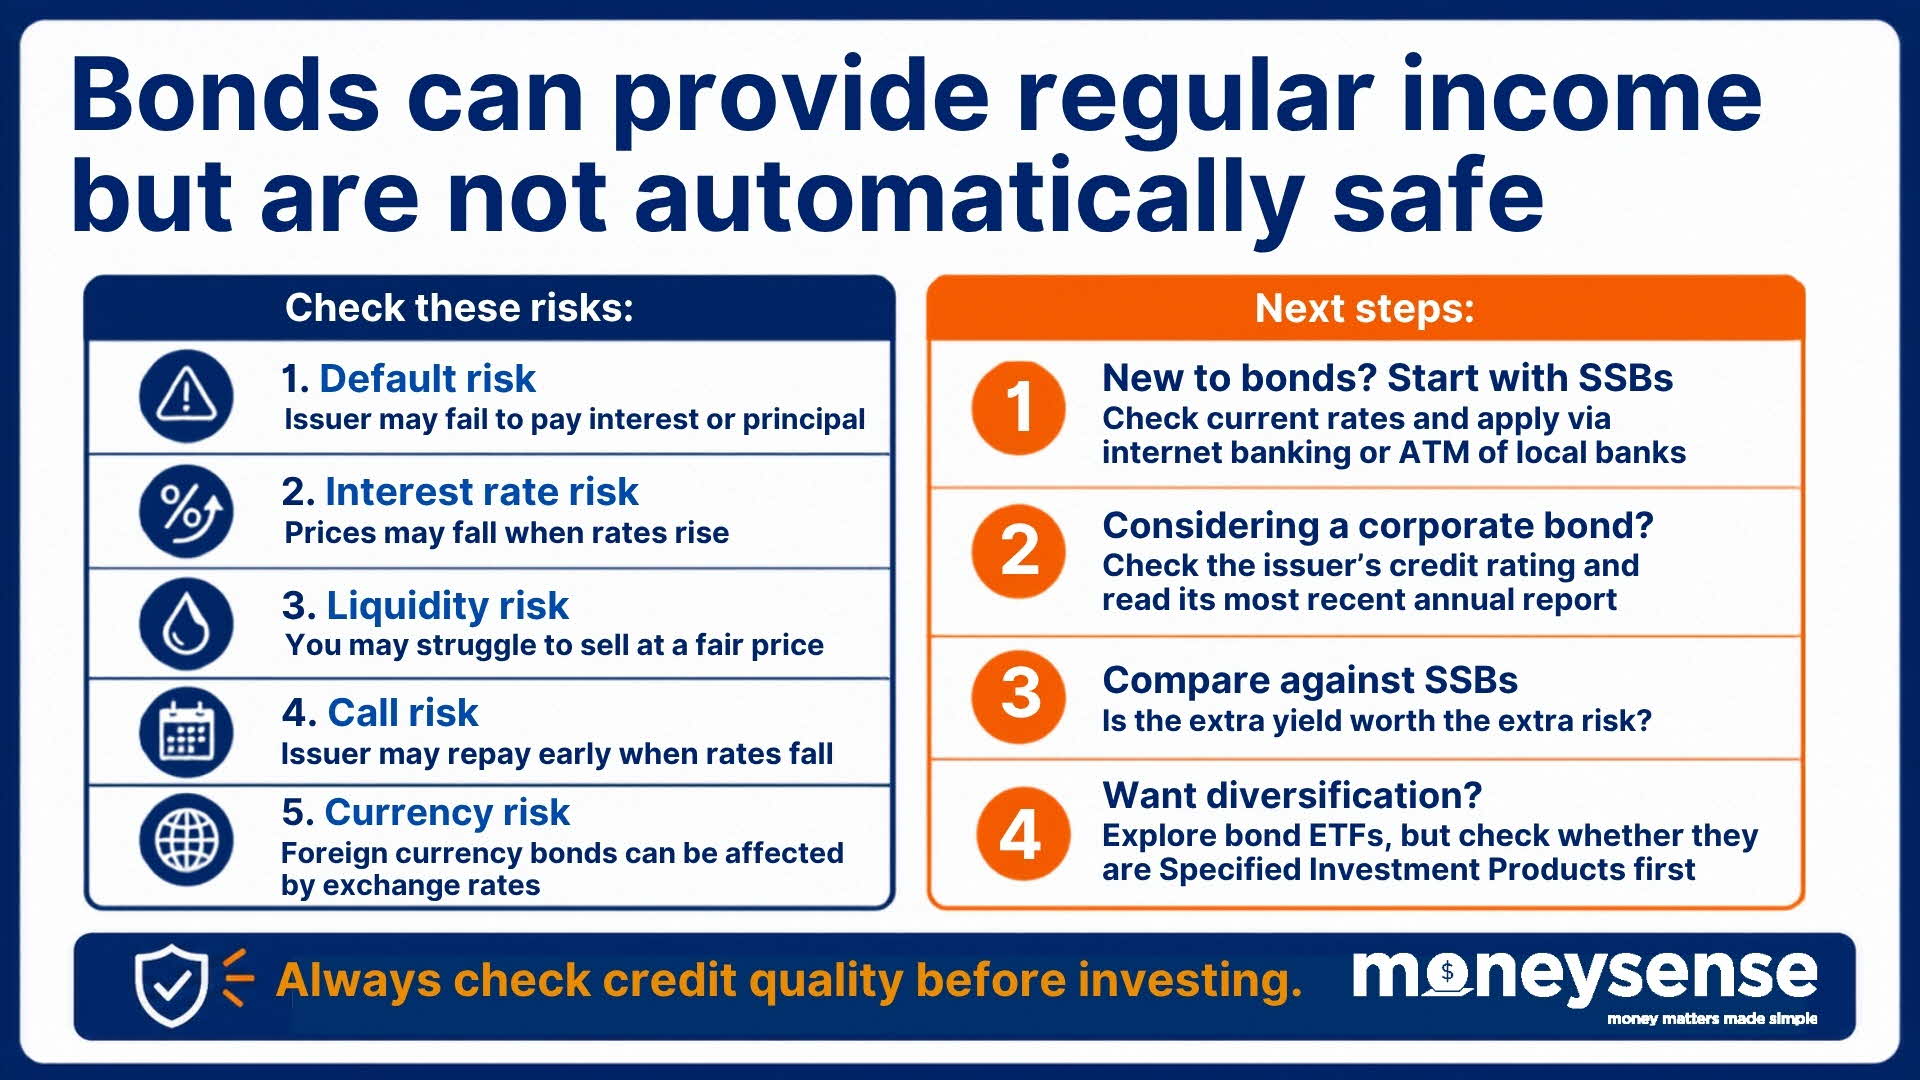
Default risk | The issuer fails to pay interest or return your principal at maturity. If the issuer is wound up, bondholders rank ahead of shareholders but behind secured creditors. You may recover nothing, or only a fraction of your investment. |
Interest rate risk | When prevailing rates rise, the market price of existing bonds falls. If you need to sell before maturity, you may have to do so at a loss. This risk increases with the bond’s remaining duration. |
Liquidity risk | Some bonds — particularly corporate bonds — trade infrequently. If you need to sell, you may struggle to find a buyer at a fair price, or at all. |
Call / early redemption risk | Some bonds allow the issuer to repay (call) the bond before maturity. This often happens when interest rates fall — the issuer can refinance more cheaply. You then face reinvestment risk: finding another bond with a similar yield may be difficult. |
Foreign currency risk | If you invest in a bond denominated in a foreign currency, exchange rate movements can affect both your interest income and the value of your principal when converted back to SGD. |
Watch out for
Assuming all bonds are safe. Non-investment grade and unrated bonds can carry more risk than many shares.
Chasing high yields without investigating the issuer. A high coupon is compensation for risk, not a free bonus.
Forgetting that bond prices fluctuate if you sell before maturity. Holding to maturity eliminates this risk — but only if the issuer does not default.
Investing CPF savings in higher-risk bonds without checking whether the expected return justifies the added risk compared to the guaranteed CPF interest rates.
Your next steps
If you are new to bonds, start with SSBs. Check current rates and apply via internet banking or ATMs of the three local banks, or visit MAS’ website (opens in new tab) for details.
If you are considering a corporate bond, look up the issuer’s credit rating at a rating agency website and read its most recent annual report before investing.
Compare the yield of any bond you are considering against what SSBs currently offer. Is the extra yield worth the extra risk?
If you want diversified bond exposure with less capital, explore bond ETFs on the SGX — but check whether they are classified as SIPs at sips.abs.org.sg (opens in new tab) first.
For an overview on understanding bonds
Frequently asked questions (FAQ)
How are bonds different from fixed deposits?
Fixed deposits are offered by banks and are covered by Singapore Deposit Insurance Corporation insurance up to $100,000. Bonds are market instruments — their prices fluctuate, they carry credit risk, and they're not deposit-insured. In exchange, bonds typically offer potentially higher returns and longer investment horizons.
Can retail investors in Singapore buy government bonds directly?
Yes — Singapore Savings Bonds and Singapore Government Securities (SGS) bonds are accessible to retail investors. SGS bonds can be purchased at primary auctions through participating banks. For diversified exposure to many bonds at once, a bond Exchange-Traded Fund or bond unit trust is more practical for most retail investors.
Are bonds truly safe? What are the risks?
Government bonds from stable governments carry very low default risk, but they're not risk-free. They carry interest rate risk (prices fall when rates rise), inflation risk (fixed coupons may not keep up with inflation), and for foreign bonds, currency risk. Corporate bonds add credit risk on top of these.
What are bond Exchange-Traded Funds (ETFs) and how do they work?
Bond ETFs hold a portfolio of bonds and trade on a stock exchange. They offer diversification, liquidity, and low minimum investment. However, unlike holding a bond to maturity, a bond ETF has no fixed maturity — its value fluctuates with interest rates indefinitely.
How much of my portfolio should be in bonds?
It depends on your age, risk tolerance, and goals. A common rule of thumb suggests increasing your bond allocation as you age — the “110 minus age” equity rule implies, for example, that a 40-year-old might hold 70% in stocks and the remaining 30% in bonds. With lifespans increasing, many financial planners have argued for keeping equity allocations higher for longer.
Related articles
An introduction to types of investments
Discover the basics of investment in Singapore, including types of assets and starting essentials. Make informed decisions for your financial future now.
Guide to ETFs: Understanding Exchange-Traded Funds
ETFs offer diversification at low cost—but not all are the same. Understand how ETFs track indices, their liquidity advantages, and how they compare to unit trusts in Singapore.
Managing investment risk
Learn about managing investment risks, diversification, correlation, asset allocation and dollar-cost averaging to make informed investment decisions.