
What to ask when buying an investment product
Never let enthusiasm replace due diligence. Use this essential checklist—covering fees, risks, liquidity, and adviser credentials—before putting your money into any investment product.
Last updated 14 September 2026
Key takeaways
Know your goals, your risk appetite, and how much you can afford to invest before meeting any Financial Adviser (FA) representative.
Check that your FA representative’s name is on the Financial Institution Representatives Register on the website of the Monetary Authority of Singapore (MAS) before you proceed.
Never invest in something you do not fully understand. Always insist on written confirmation of any guarantees.
Investment products — shares, bonds, structured deposits, unit trusts, and investment-linked insurance policies (ILPs) — all carry risk. The best way to manage that risk is to understand exactly what you are buying before you sign anything.
Use the checklists below before and during any meeting with an FA representative.
Questions to ask yourself
About your goals and situation
Is my FA firm authorised by MAS? Check the MAS Financial Institutions Directory (eservices.mas.gov.sg/fid (opens in new tab)) before any meeting.
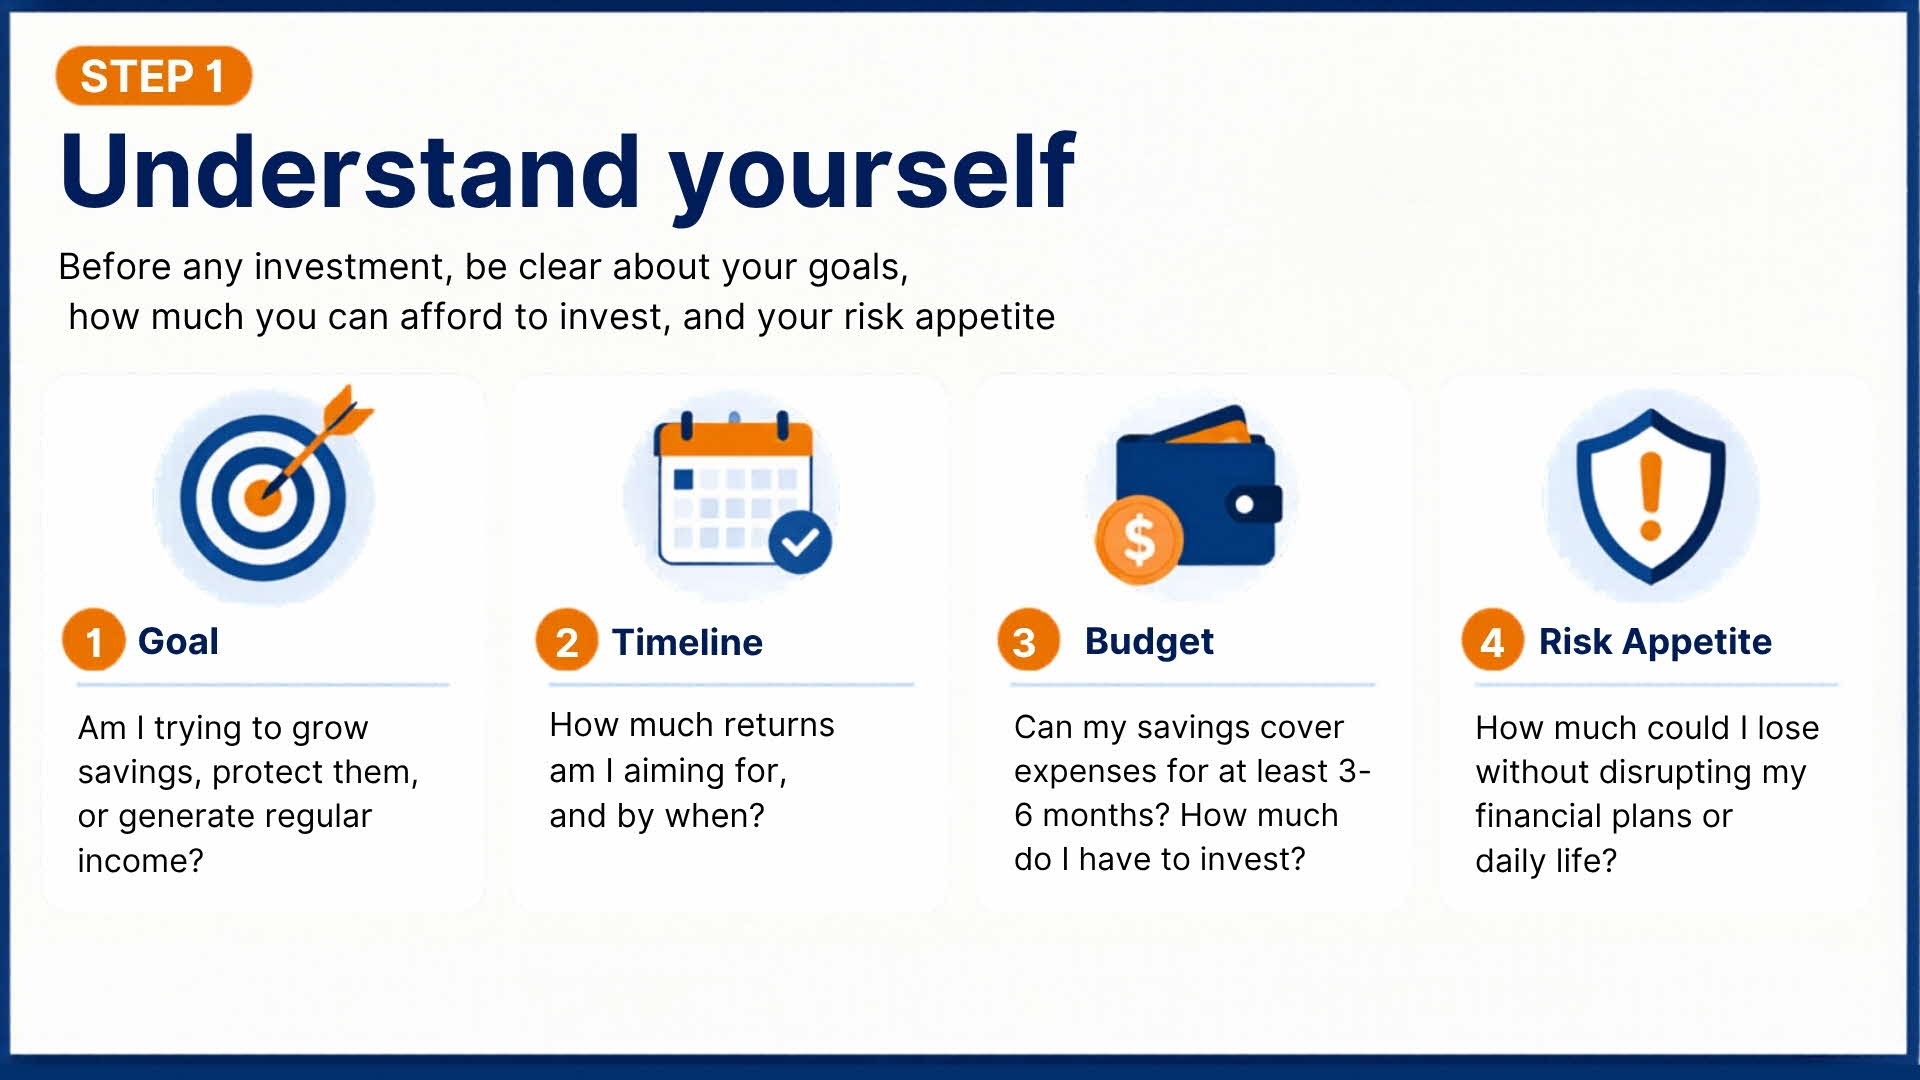
What are my investment goals? Am I trying to grow savings, protect them, or generate regular income? How much do I need and by when?
How much can I afford to invest? After setting aside an emergency fund covering at least 3-6 months of expenses, how much is really available to invest?
What is my risk appetite? How much could I lose without disrupting my financial plans or daily life?
About the specific product
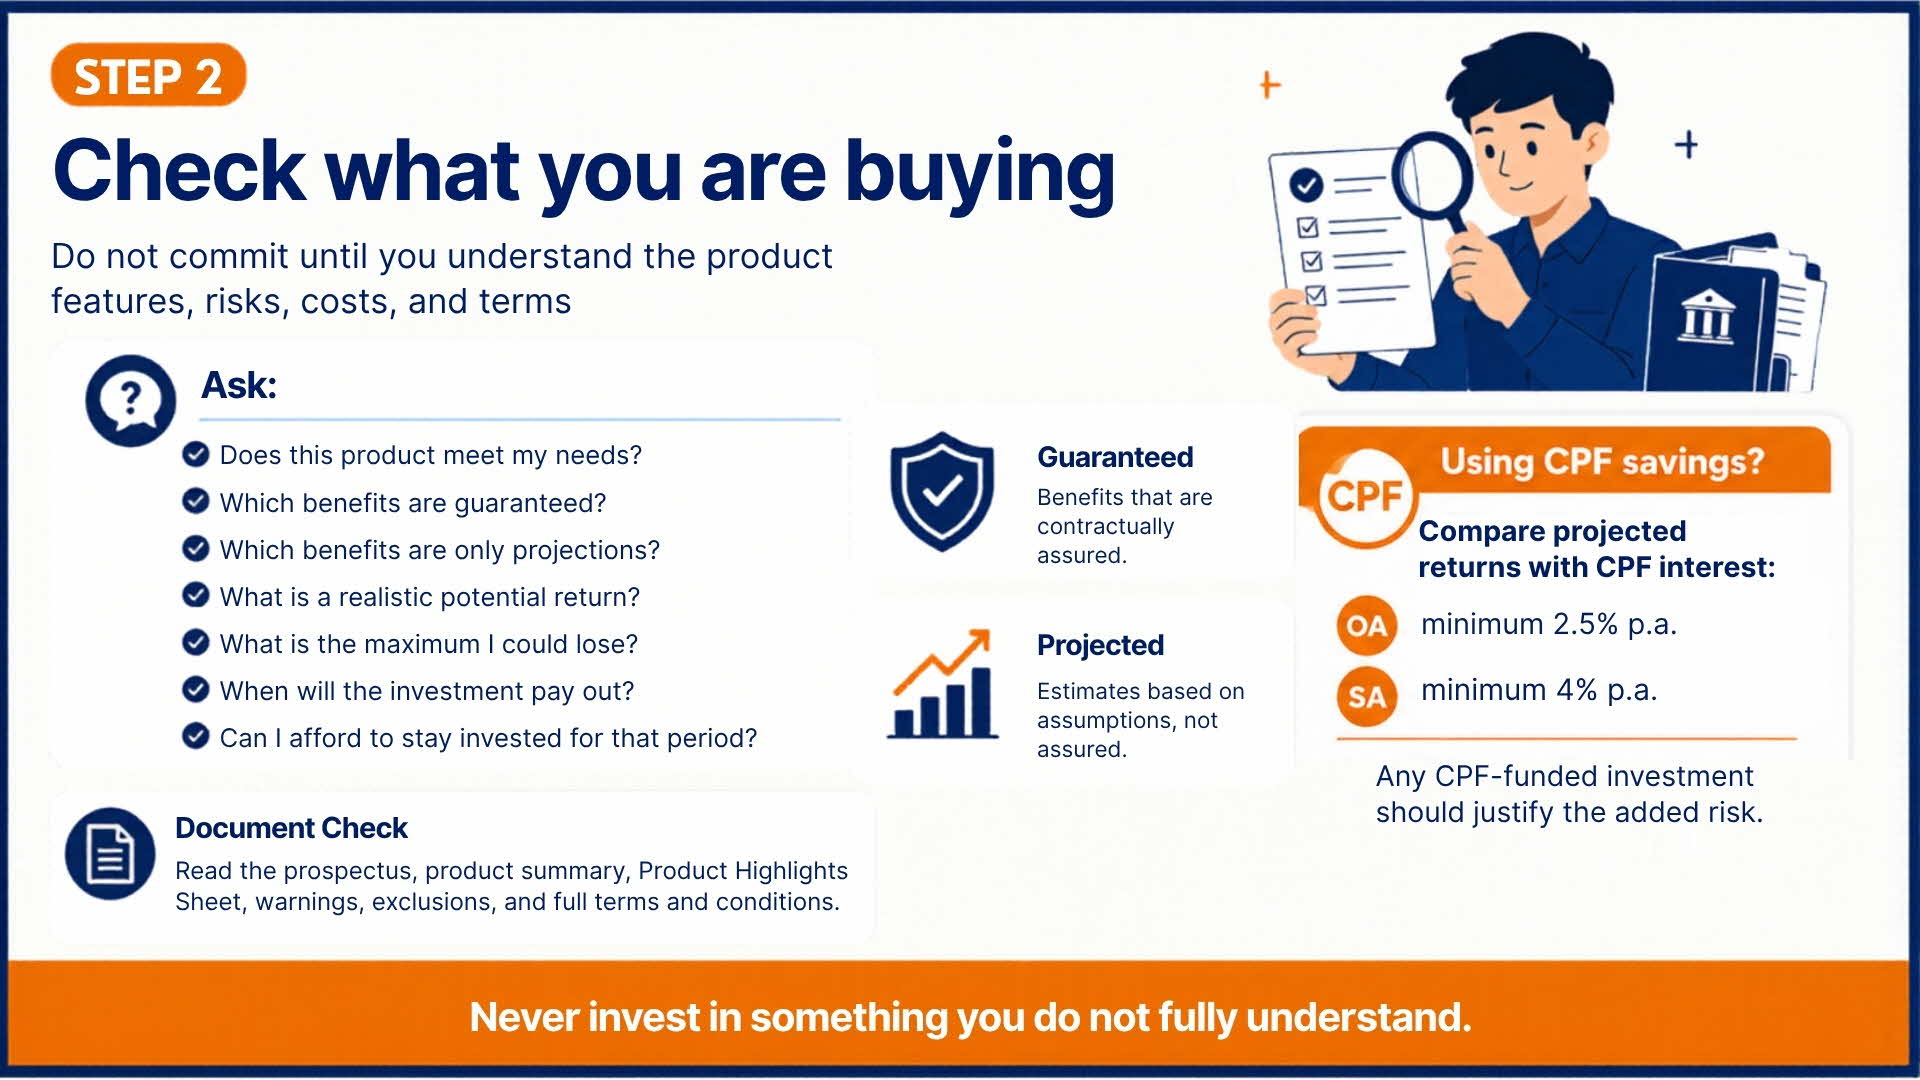
Does the recommended product actually meet my needs? Which of its benefits are guaranteed, and which are only projections?
What returns and losses should I expect? What is a realistic potential return, and what is the most I could lose? Do not rely on verbal promises of high returns — insist on written confirmation of any guarantees.
Should I use my CPF savings? If so, how does the product’s projected return compare with the interest guaranteed in my CPF accounts?
CPF context: Your CPF Ordinary Account (OA) earns a minimum of 2.5% per annum, and your Special Account (SA) earns a minimum of 4% per annum. Both are guaranteed and risk-free. Any investment recommended using CPF funds should clearly justify the added risk for an expected return that is meaningfully better.
When will the investment pay out, and how long must I stay invested? Can I afford to keep my money invested for that period? Do I incur any penalties or fees for early withdrawal or termination of the investment product?
Have I read the key documents, such as the prospectus, product summary, Product Highlights Sheet, warnings and exclusions?
Have I compared this product to alternatives? How does it measure up on risk, return, fees, and flexibility?
Questions to ask your FA representative
About suitability and product fit
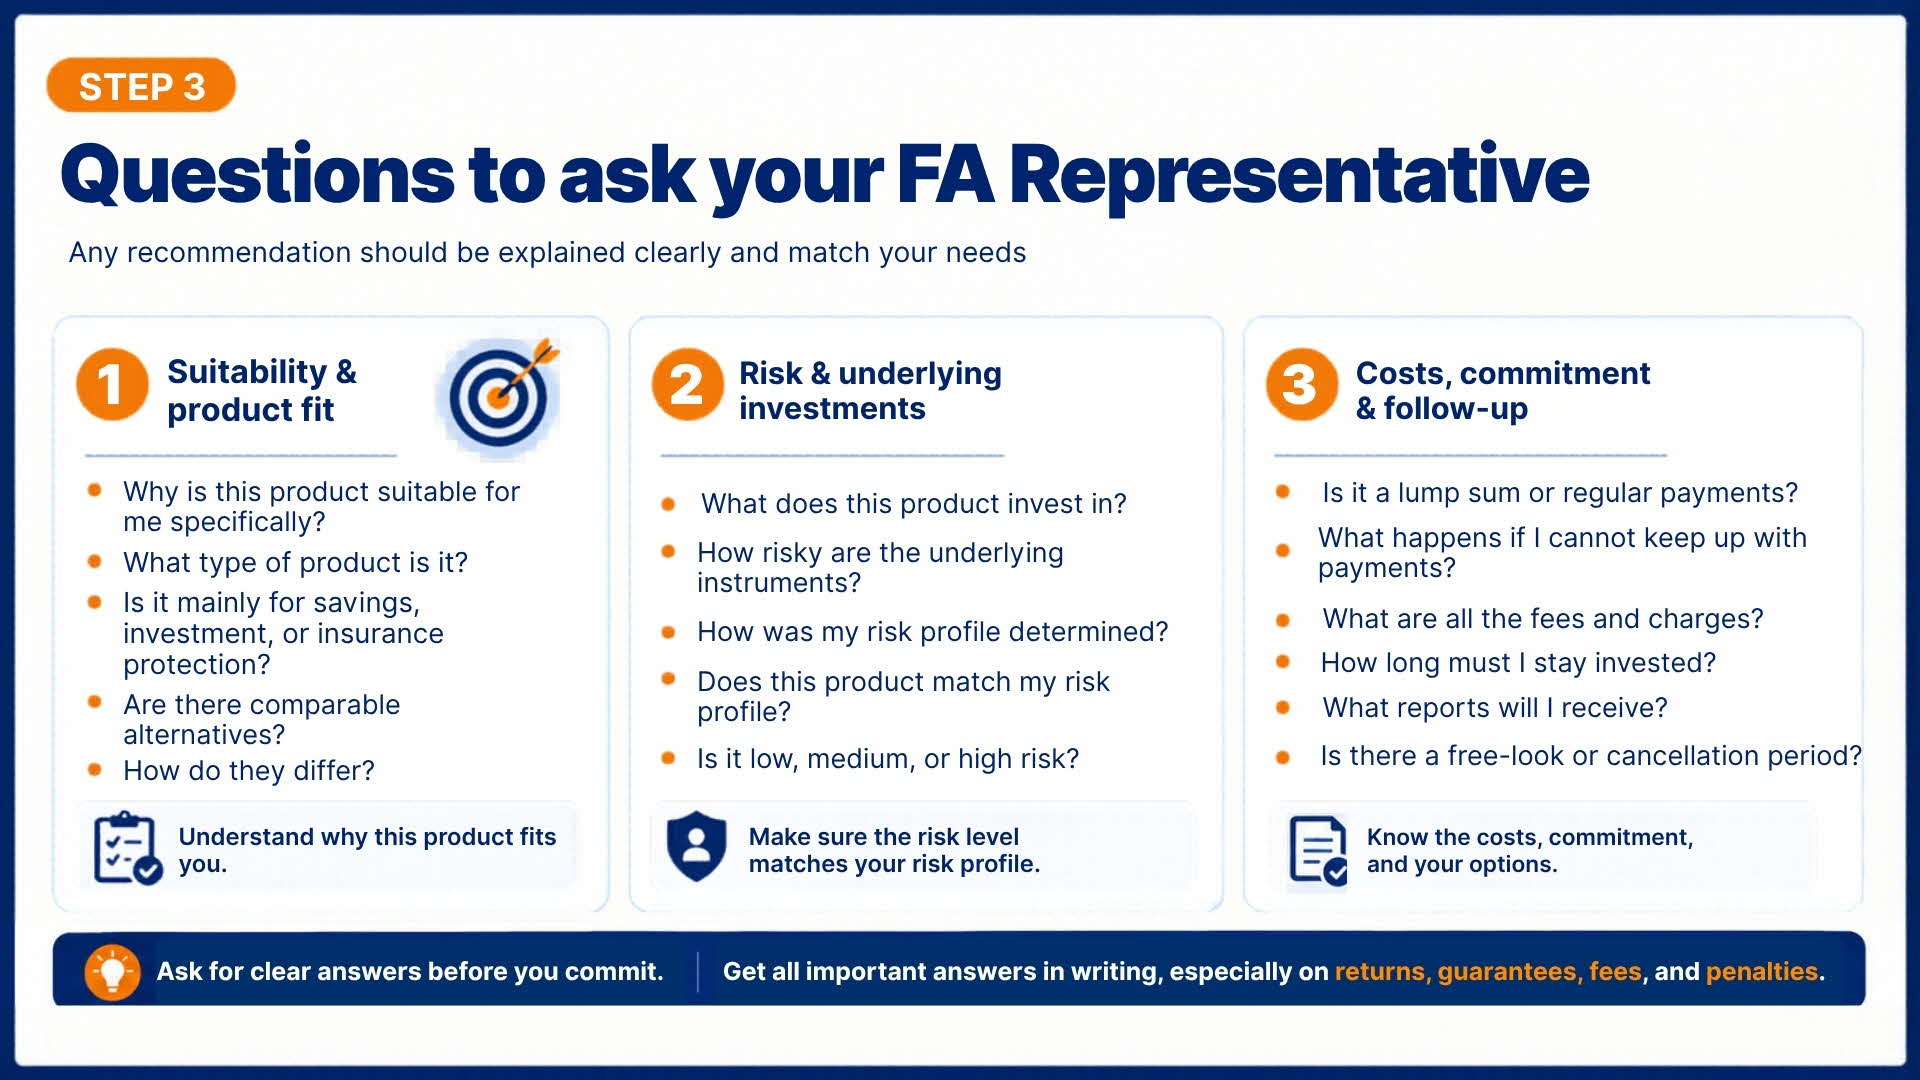
Why is this product suitable for me specifically? What type of product is it, e.g., life insurance, unit trust, or structured deposit? Is it mainly for savings, investment, or insurance protection?
What does this product invest in? How risky are the underlying instruments?
What are the benefits, and which ones are guaranteed versus projected? Are there comparable alternatives, and how do they differ?
How was my risk profile determined, and does this product match it? Is it low, medium, or high risk?
About costs and commitment
How much do I need to commit, and is it a lump sum or regular payments? What happens if I cannot keep up with payments? What are all the fees and charges?
If investing CPF savings: how do the projected returns compare to CPF OA and SA interest rates?
How long must I stay invested? What fees or penalties apply if I withdraw early?
About the FA representative/ firm
Is the representative listed on the MAS’ Financial Institution Representatives Register? Check at eservices.mas.gov.sg/rr (opens in new tab)
How will my investment be monitored? What reports and updates will I receive, and how often?
If the product turns out to be unsuitable after I have bought it, what are my options? Is there a free-look or cancellation period? How much time do I have, and will I get back the full amount or only part of it?
Watch out for
Assuming an FA representative’s credentials without checking. Use eservices.mas.gov.sg/rr (opens in new tab) to verify.
Verbal promises of guaranteed or high returns. Only written guarantees in the product documents count.
Feeling pressured to sign on the spot. You are never obligated to buy immediately. Take the documents home, read them, and decide in your own time.
Your next steps
Before your next meeting, verify your FA representative at eservices.mas.gov.sg/rr (opens in new tab) and the firm at eservices.mas.gov.sg/fid (opens in new tab).
Write down your top three financial goals and the investment timeline for each. Bring this to the meeting.
Prepare your questions using the checklists above. Ask for all answers to be confirmed in writing, especially any claims about returns or guarantees.
After the meeting, take the product documents home before signing anything. Only proceed if the recommendation still makes sense after 24–48 hours.
For an overview on what to ask when buying an investment product
Frequently asked questions (FAQ)
What should I check before meeting a financial adviser (FA) representative?
Before any meeting, use the MAS online directories (eservices.mas.gov.sg/fid (opens in new tab) and eservices.mas.gov.sg/rr (opens in new tab)) to verify the FA firm and your FA representative. Write down your financial goals, risk appetite, and the amount you can afford to invest. This helps keep the discussion focused and you are less likely to be pressured into buying something unsuitable.
What CPF interest rates should I compare against before investing CPF savings?
Your CPF Ordinary Account (OA) earns a minimum of 2.5% per annum, guaranteed and risk-free. Your Special Account (SA) earns a minimum of 4% per annum, also guaranteed and risk-free. Any investment recommended using CPF savings must clearly justify taking added risk with expected returns that are meaningfully better. If the projected return does not significantly exceed these guaranteed rates, the risk may not be worth it.
What documents should I receive before buying an investment product?
For investment products, you should receive FNA (Financial Needs Analysis) documentation showing the basis for the recommendation, and a prospectus or Product Highlights Sheet disclosing the product's features, risks, and costs. For insurance, you also receive a cover page, product summary, and policy illustration. Read them carefully before signing anything.
Can I cancel an investment after buying it?
Most products include a free-look period: 14 days for insurance (from the date you receive policy documents) and 7 days for investments (from the point of investment). You can cancel without administrative penalty, but you bear any market loss if the product has fallen in value during that period. Confirm the free-look terms before you sign.
What should I do if an FA representative pressures me to sign on the spot?
You are never obligated to sign immediately. Take the product documents home, read them, and wait at least 24–48 hours to see if a recommendation still makes sense. If you feel pressured, that is a warning sign. You can always ask for an alternative recommendation or choose not to proceed.
How do I check whether an FA representative is legitimate?
Check the MAS Financial Institutions Directory at eservices.mas.gov.sg/fid (opens in new tab) to confirm the firm is authorised, and the MAS Financial Institution Representatives Register at eservices.mas.gov.sg/rr (opens in new tab) to confirm the individual holds a valid representative number. Ask the FA representative to explain why the recommended product is suitable for you. Ask as many questions as you need. Do not rely on verbal assurances — verify independently before you invest.
Related articles
Financial advice: Who you could be dealing with
There are different types of MAS-regulated financial advisers in Singapore—tied agents, independent advisers, and robo-advisers. Learn what suits you and how to verify credentials.
Financial advisory process
Before you discuss insurance or investments with your financial adviser, learn about the process for analysing your needs and recommending products to you.
Managing investment risk
Higher returns always come with higher risk—but which risks are you actually taking? Understand market, credit, liquidity, and currency risk before building your Singapore portfolio.