Guide to ETFs: Understanding Exchange-Traded Funds
ETFs offer diversification at low cost—but not all are the same. Understand how ETFs track indices, their liquidity advantages, and how they compare to unit trusts in Singapore.
Last updated on 14 October 2026
Key takeaways
An Exchange-Traded Fund (ETF) is an investment fund listed and traded on a stock exchange, like a share.
ETFs pool money from many investors and uses it to invest according to a stated objective — most commonly, to track the performance of a specific index.
Most ETFs aim to track — not beat — a specific index, such as the Straits Times Index (STI). This makes them a low-cost way to gain broad market exposure.
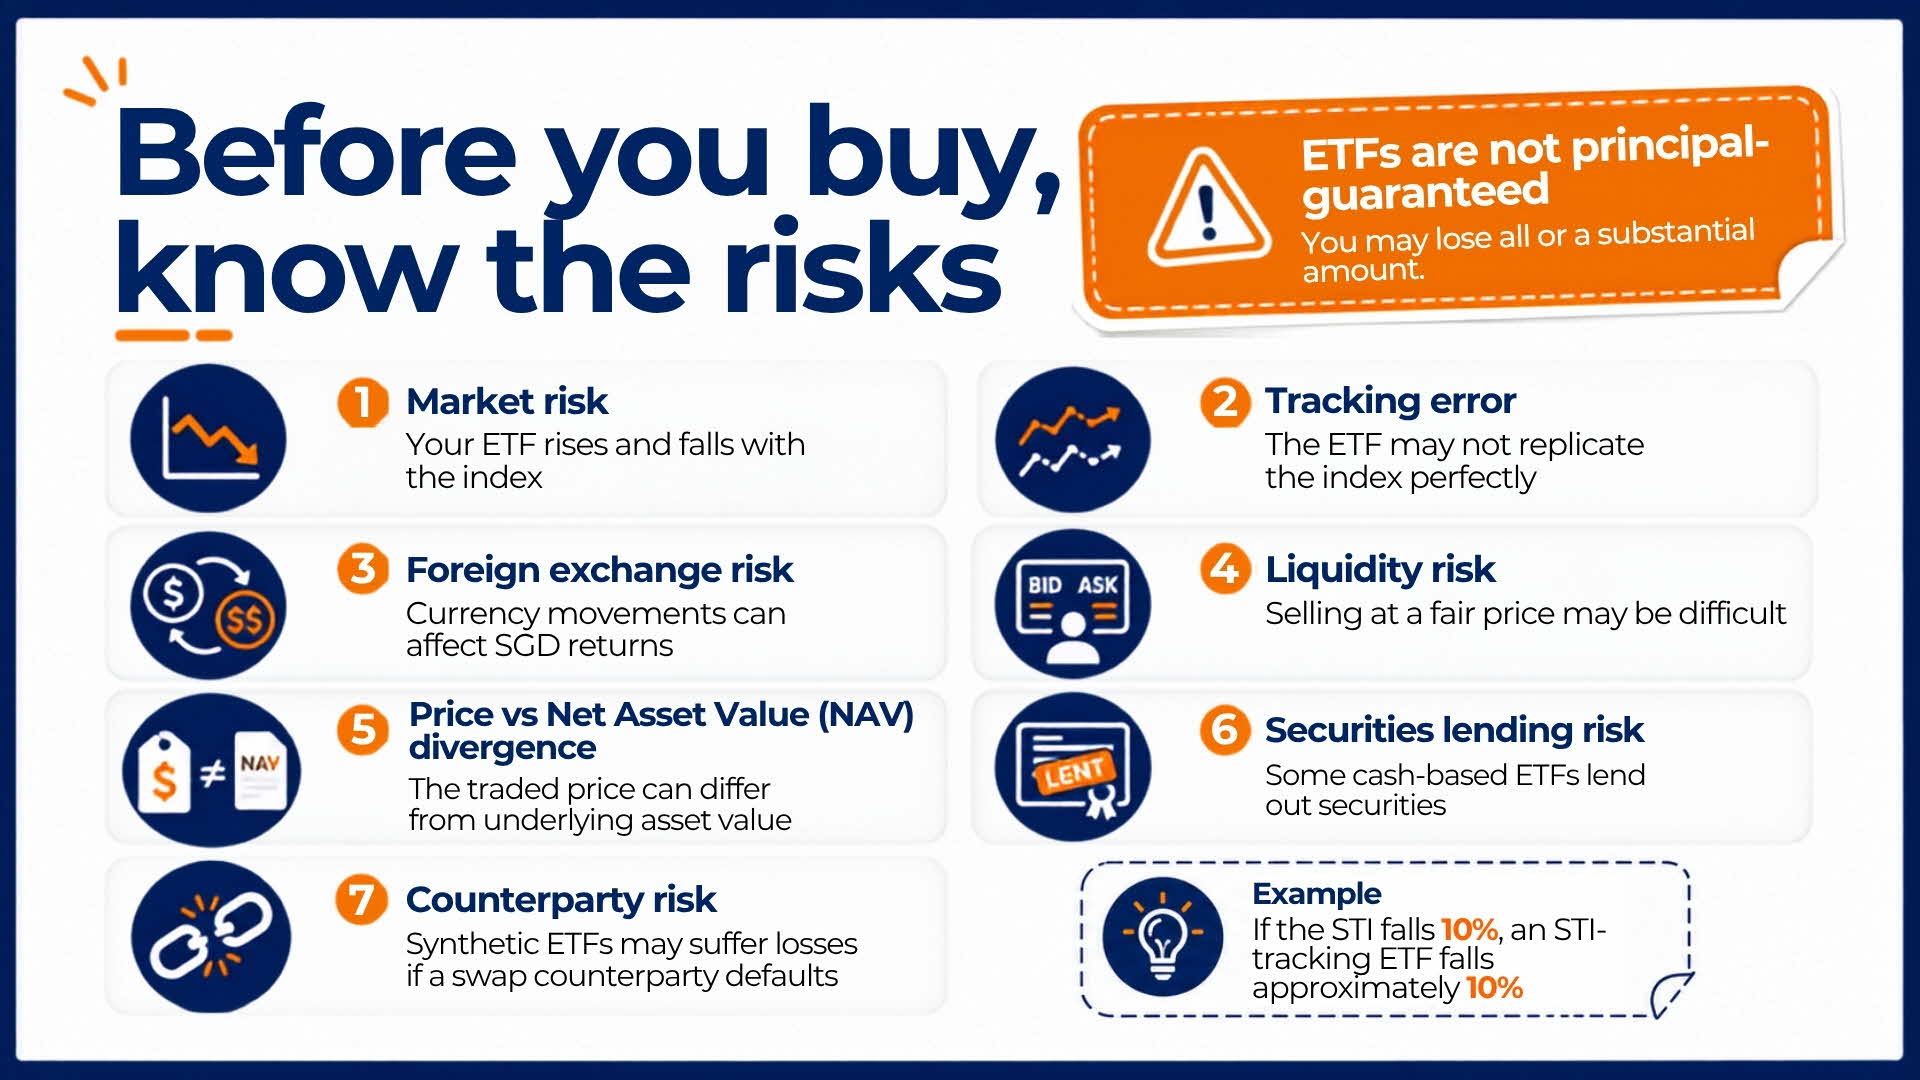
ETFs are not principal-guaranteed. You can lose all or a significant portion of your investment.
What is an ETF?
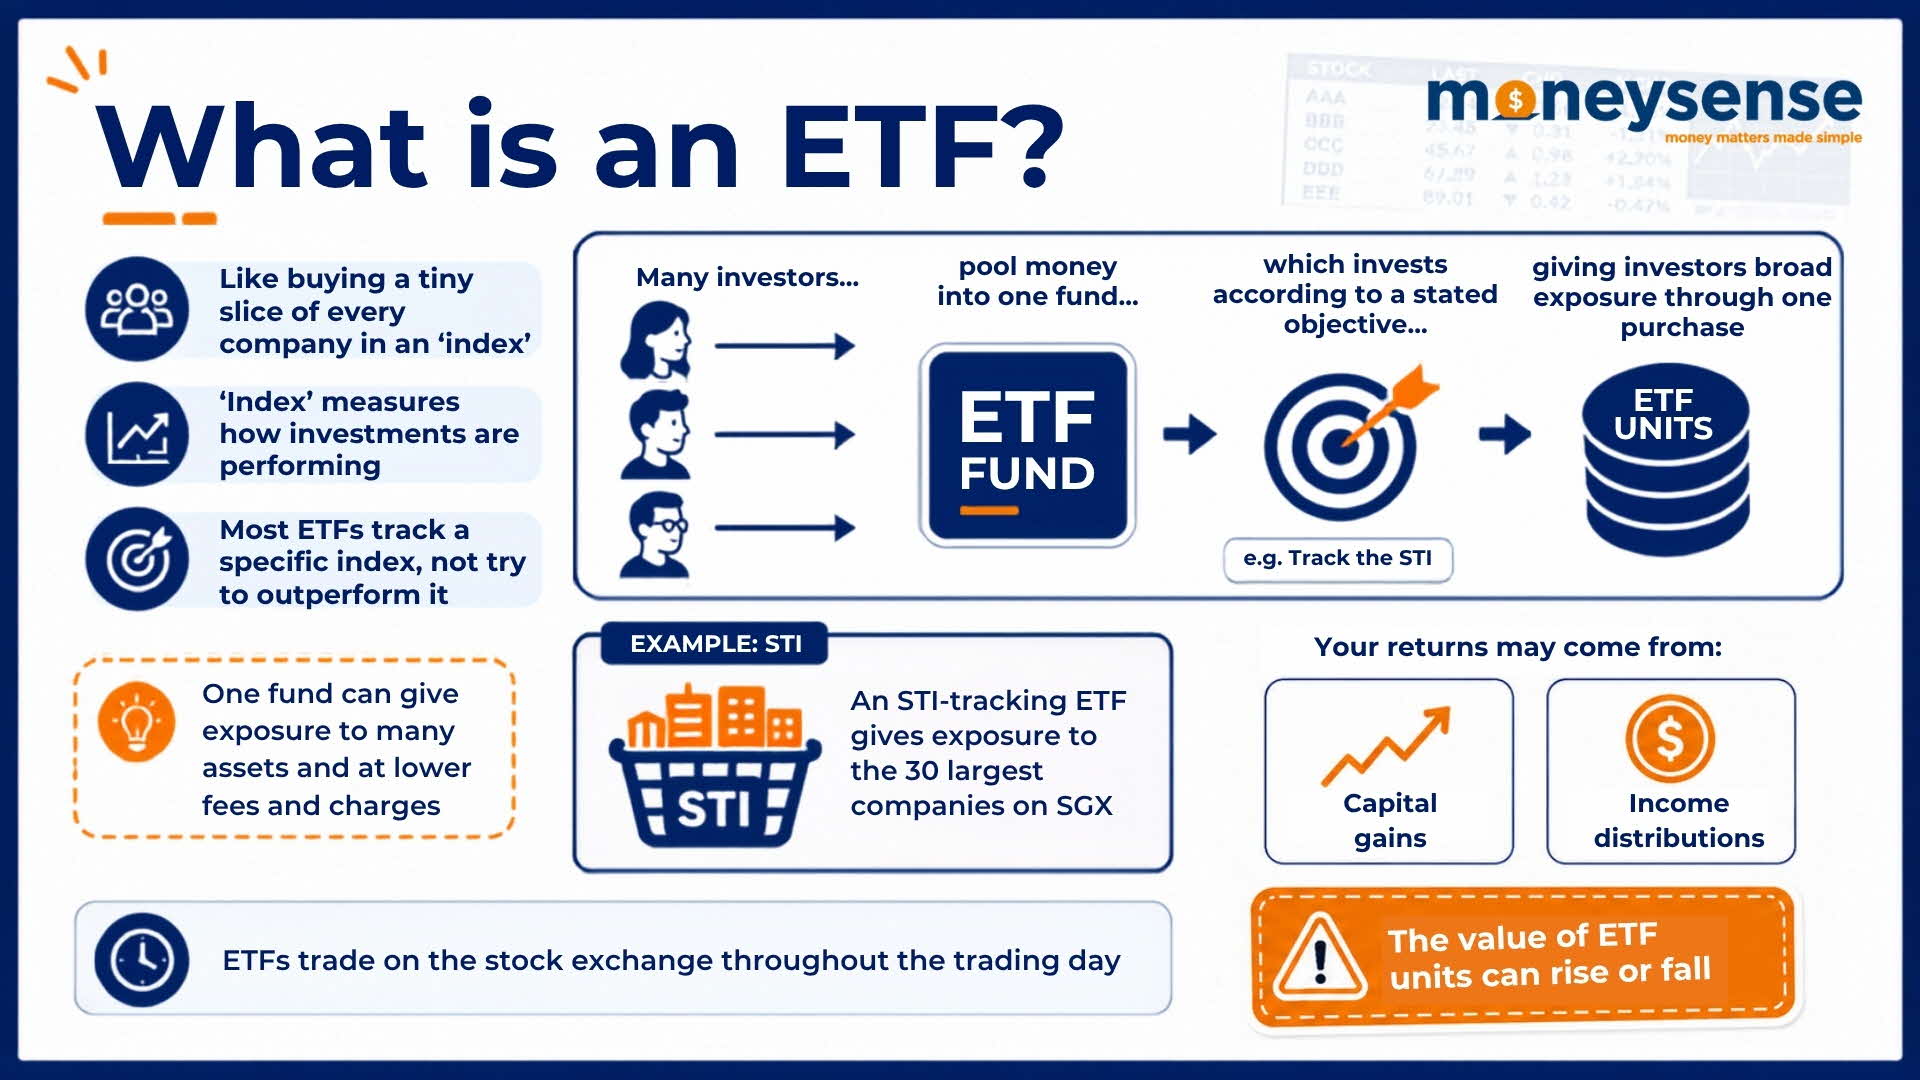
An ETF pools money from many investors and uses it to invest according to a stated objective — most commonly, to track the performance of a specific index. Think of it as buying a small slice of every company in an index through one transaction, rather than buying each share individually. This makes ETFs a low-cost way to gain broad exposure to many companies.
For example, an ETF that tracks the STI, which covers the 30 largest companies on the Singapore Exchange (SGX), gives you exposure to the overall Singapore market through a single purchase. If the STI rises, your ETF rises broadly in step; if it falls, so does the ETF.
Beyond shares, the underlying assets of ETFs can be bonds, commodities and foreign currencies. You can even choose ETFs that focus on specific global trends like clean energy.
Unlike unit trusts, ETFs are traded on the stock exchange throughout the trading day, the same way shares are. Their price changes continuously during market hours based on supply and demand. Many ETFs on the SGX are also classified as Specified Investment Products (SIPs) - you must satisfy a knowledge assessment before investing in these.
How ETF returns work
You invest in an ETF by buying units. Your return comes from two sources:
Capital gains: If the price of the ETF units rises above what you paid for them.
Income distributions: Some ETFs pay dividends or interest income generated by the underlying assets.
Passive vs active ETFs
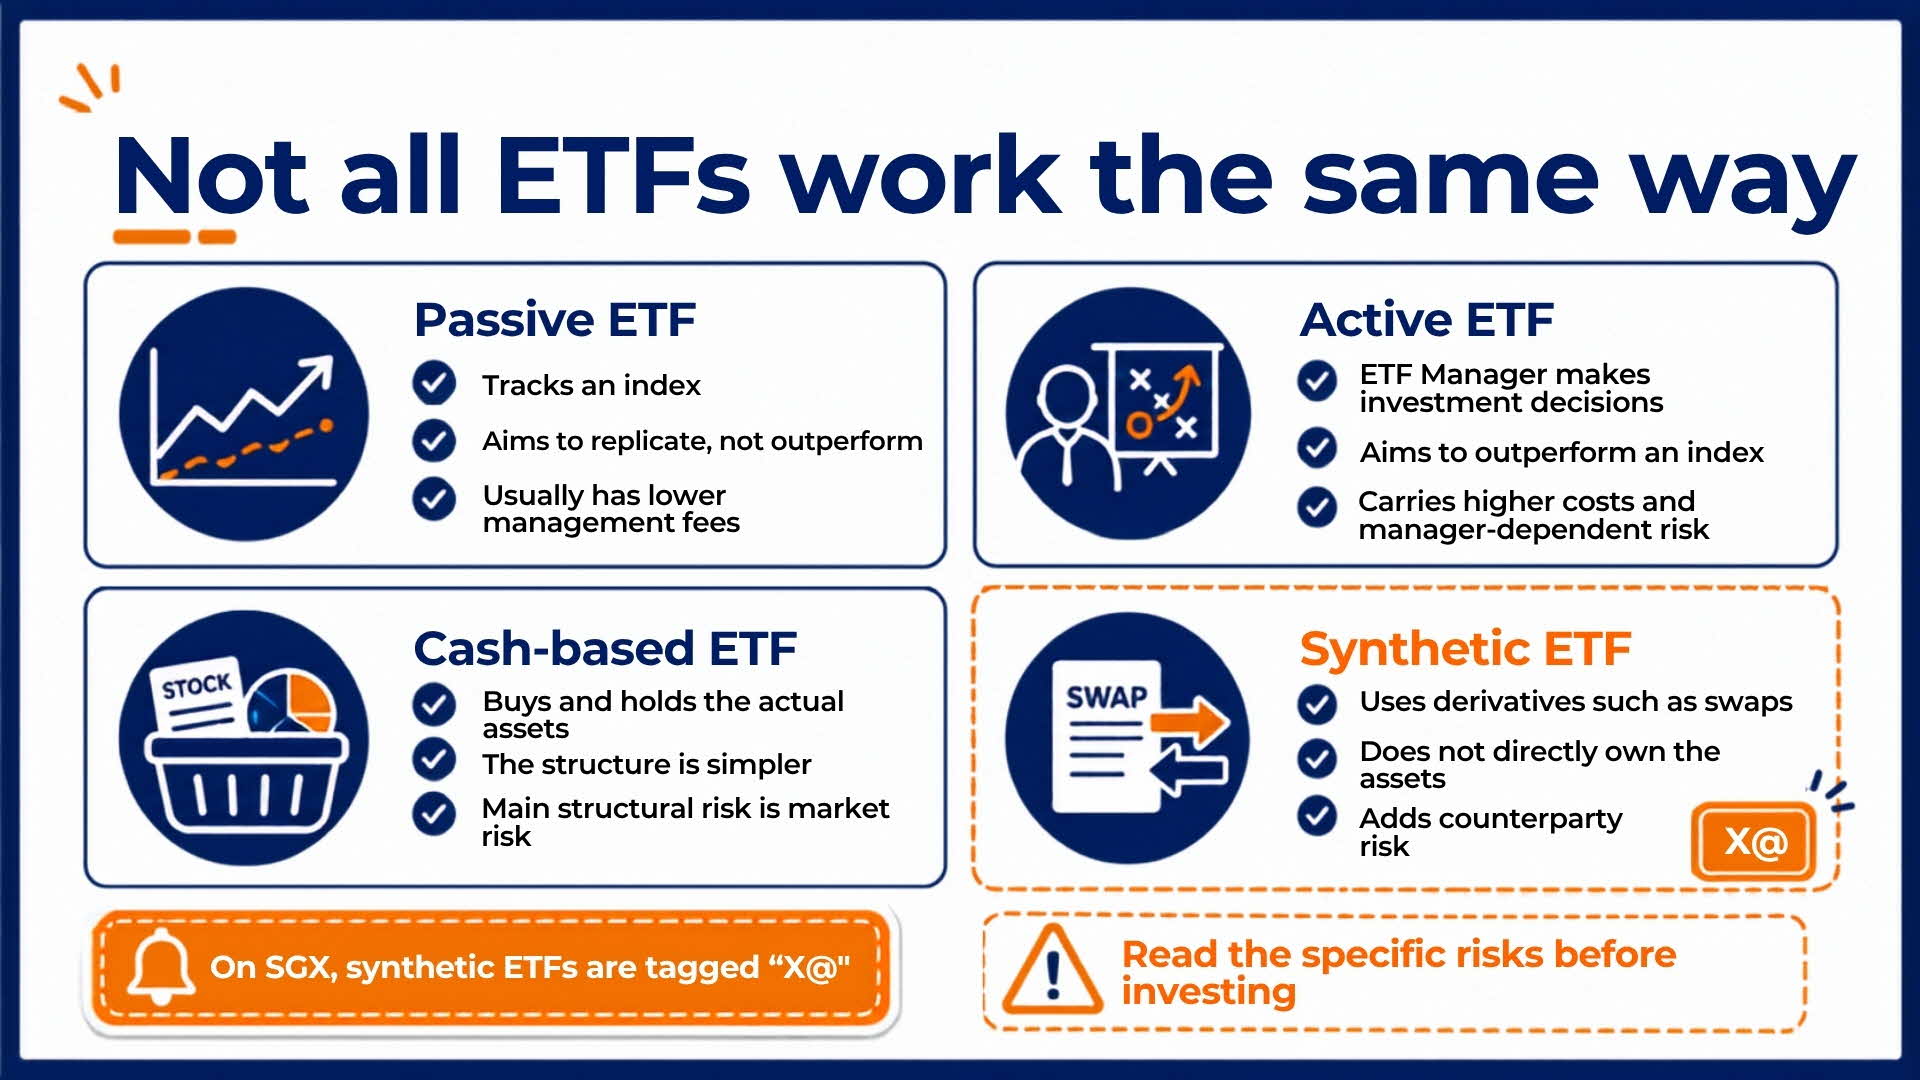
Most ETFs are passively managed. The fund manager’s job is to replicate the index as closely as possible, not to outperform it. Because there is no active stock-picking, management fees are generally lower than for actively-managed funds.
A smaller number of ETFs are actively managed, where a fund manager makes investment decisions with the aim of outperforming an index. These carry higher fees and higher manager-dependent risk.
Cash-based vs synthetic ETFs
Not all ETFs work the same way under the hood. There are two main structural approaches:
Cash-based vs synthetic ETFs
Cash-based ETF | Synthetic ETF |
Directly buys and holds the actual assets in the index (e.g. the actual shares in the STI) | Does not own the assets directly; instead, uses financial derivatives — typically swap contracts — to replicate index returns without owning the underlying assets |
Simpler structure — the ETF’s value is directly tied to the assets it holds | More complex structure involving additional counterparties (see our article on synthetic ETFs for a detailed explanation) |
Your main risk is market risk: If the index falls, so does the ETF | Adds counterparty risk: If the party on the other side of the swap defaults, the ETF may suffer losses even if the index is unaffected |
On the SGX: Synthetic ETFs are tagged with ‘X@’ beside their trading name. Read our article about synthetic ETFs to understand the specific risks before investing.
Advantages of ETFs
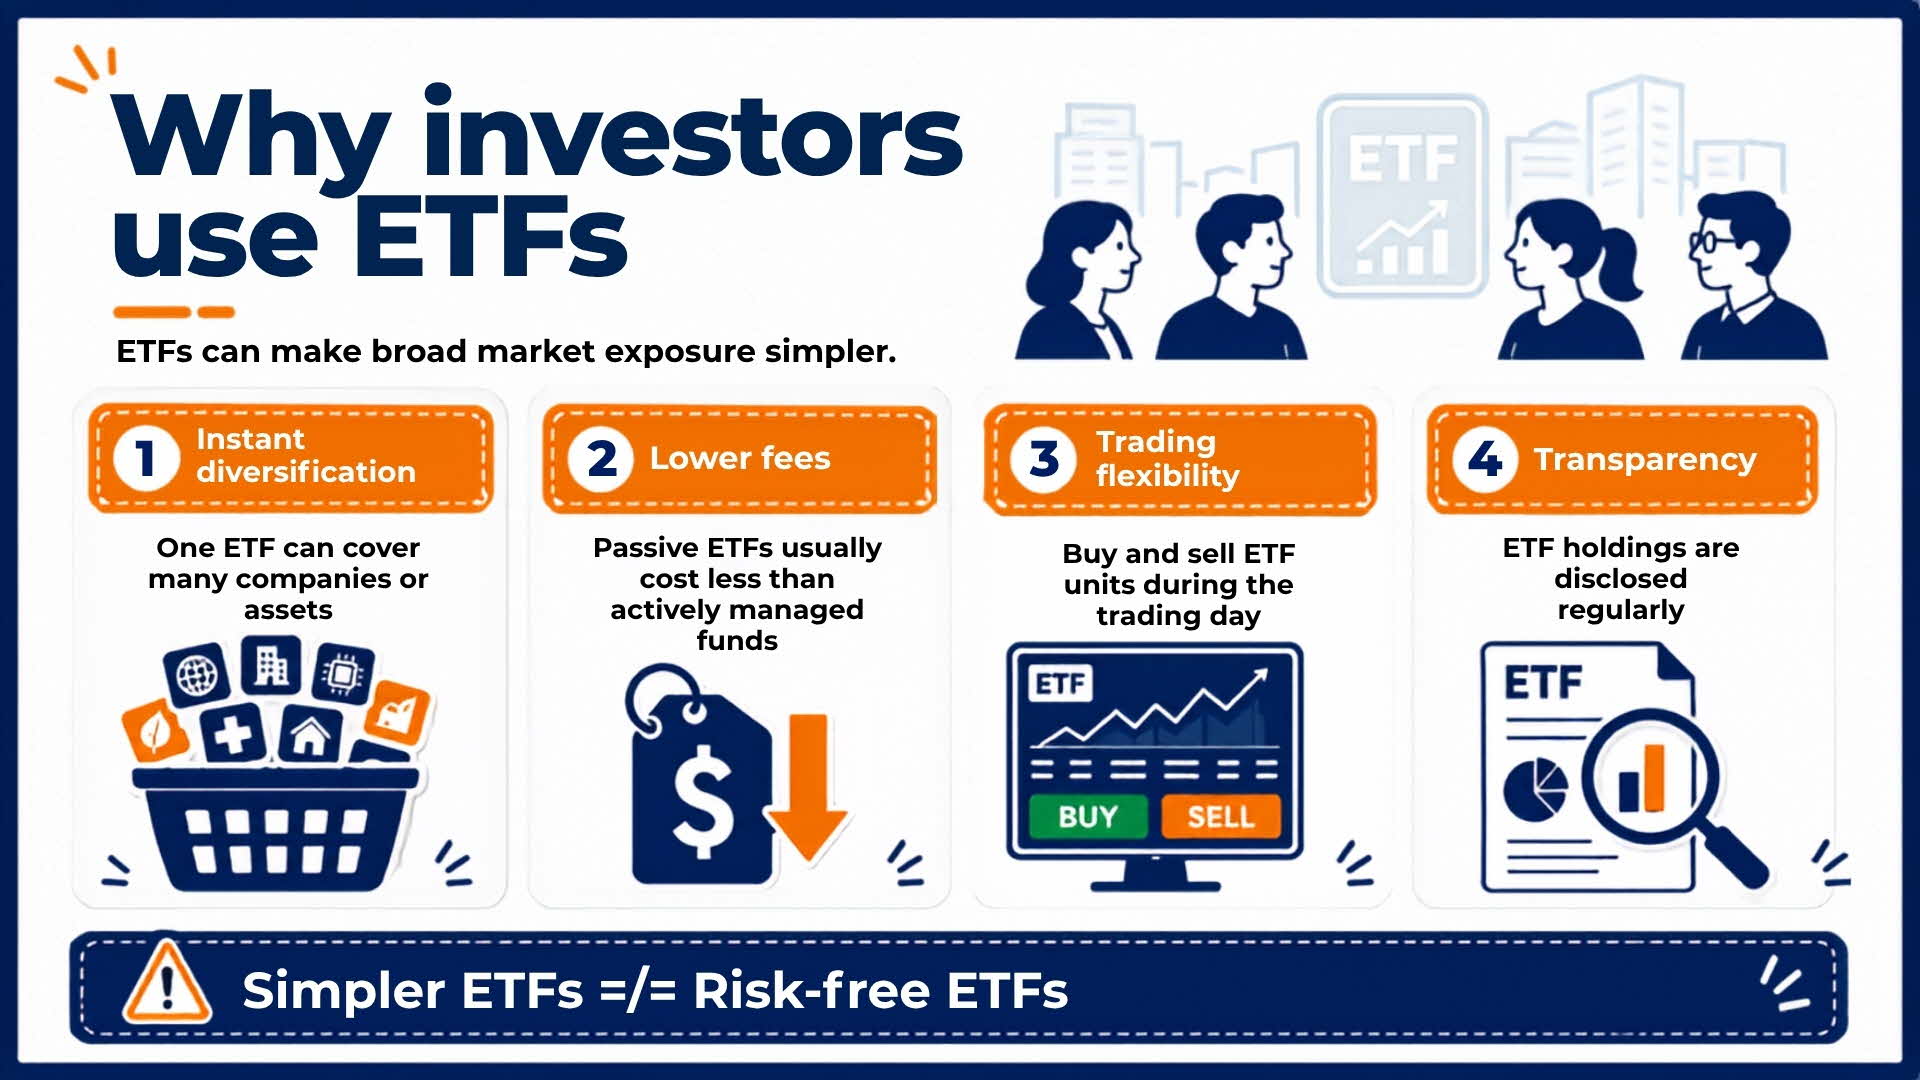
Instant diversification: A single ETF purchase gives you exposure to many companies or assets, reducing concentration risk.
Lower fees than most actively managed funds: Passively managed ETFs typically have lower management fees.
Trading flexibility: You can buy and sell ETF units throughout the trading day at the prevailing market price.
Transparency: ETFs disclose their holdings regularly, making it easy to see exactly what you own.
Risks of ETF investing
Risks of ETF investing
Market risk | Your investment rises and falls with the index being tracked. If the STI falls 10%, an STI-tracking ETF falls approximately 10%. There is no protection from market downturns. |
Tracking error | An ETF may not perfectly replicate the index it tracks. Differences can arise from execution costs, index rebalancing timing, or the fund holding a representative sample of stocks rather than the full index. A low tracking error is better. |
Foreign exchange risk | If the ETF invests in assets denominated in a foreign currency, exchange rate movements between that currency and SGD can affect your returns, even if the underlying index performs well. |
Liquidity risk | ETFs rely on designated market makers to provide continuous “buy” and “sell” quotes. If a market maker fails to perform, it may become difficult to sell your ETF units at a fair price. |
Price vs Net Asset Value (NAV) divergence | An ETF’s traded price can deviate from its NAV — the underlying value of the assets per unit — due to market supply and demand. |
Securities lending risk (for cash-based ETFs) | Some cash-based ETFs lend out the securities they hold to generate additional income. If the borrower defaults and cannot return the securities, the ETF — and therefore you — may suffer a loss. |
Counterparty risk (for synthetic ETFs) | Specific to synthetic ETFs, if the swap counterparty defaults, the ETF may suffer losses even if the underlying index is performing well. |
Are ETFs right for you?
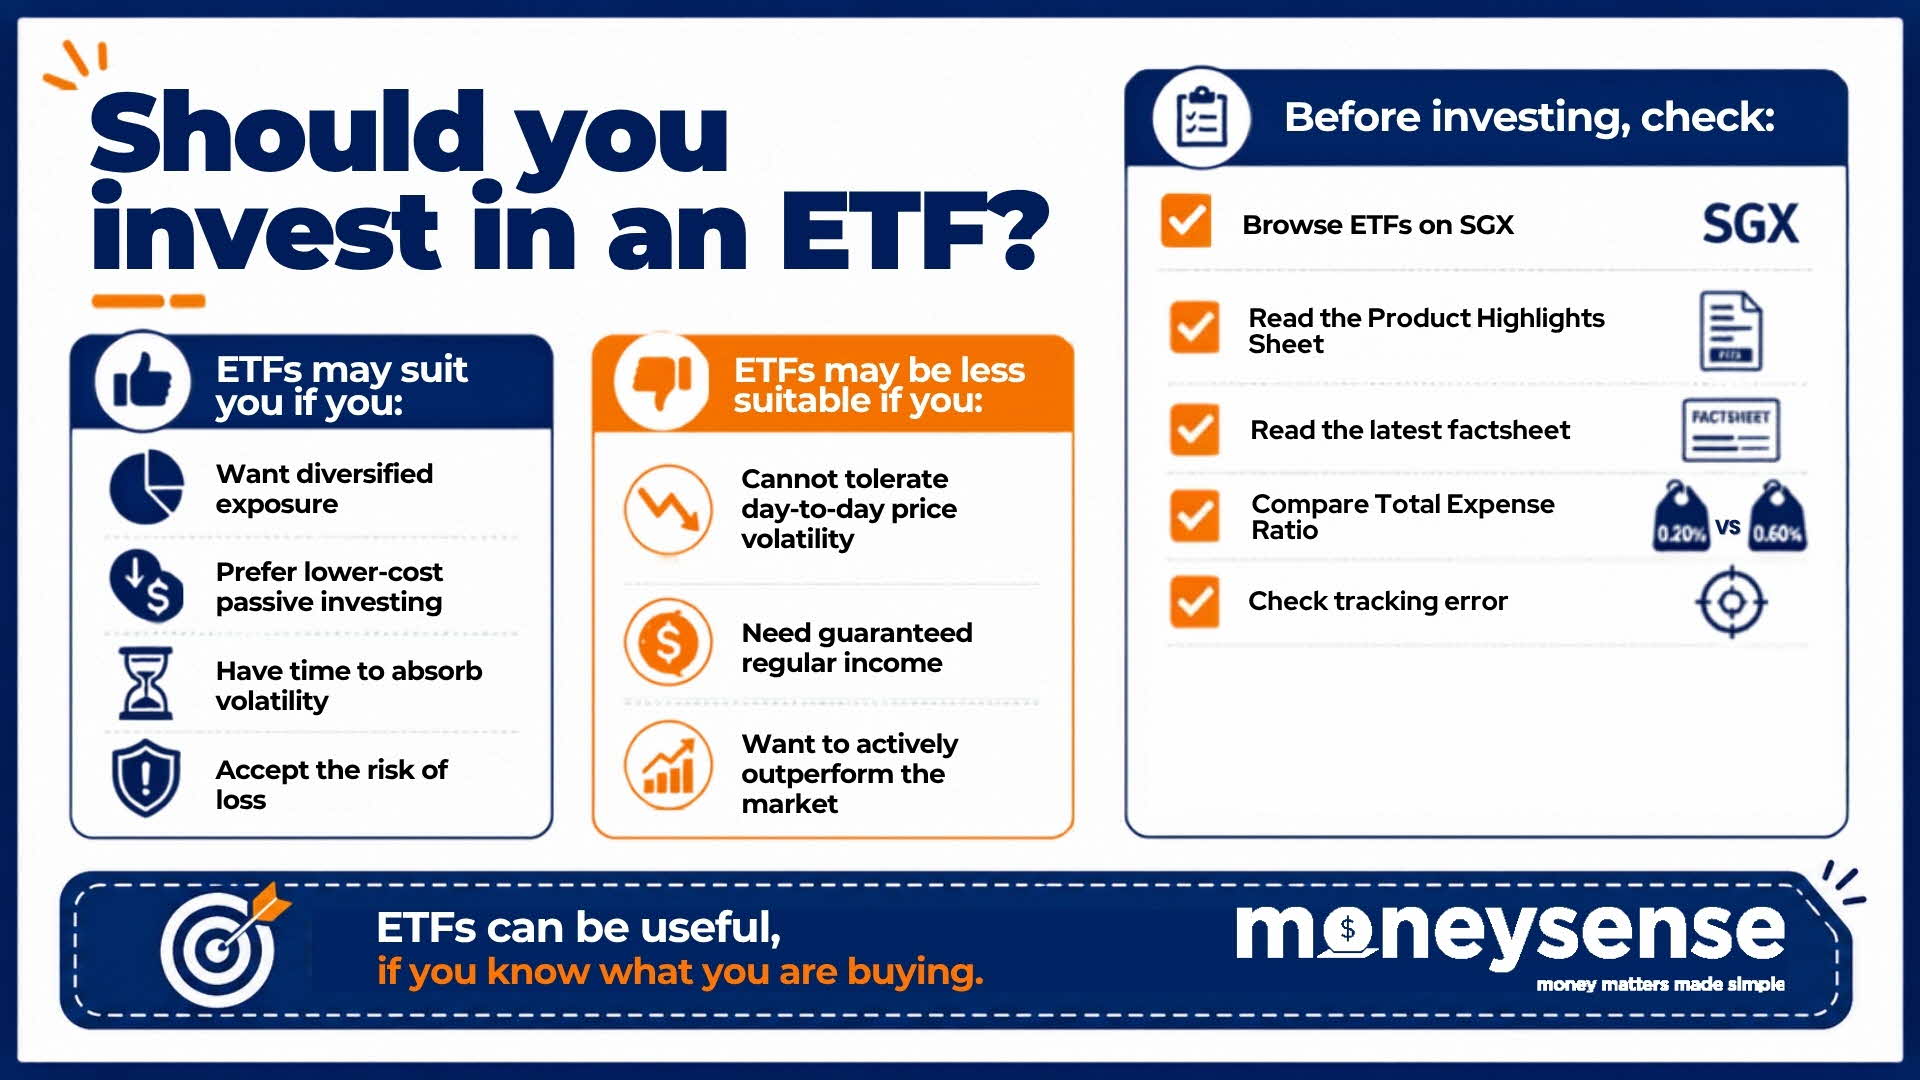
ETFs are broadly suitable for investors who:
Want diversified exposure to a market or index without buying individual stocks or assets
Prefer lower-cost passive investing over actively managed funds
Have a long enough investment horizon to absorb short-term market volatility
Understand that ETFs are not principal-guaranteed and accept the risk of loss
ETFs may be less suitable if you:
Cannot tolerate the day-to-day price volatility of a market-tracking fund
Need guaranteed regular income (most index ETFs do not pay consistent distributions)
Want to actively outperform the market (by definition, an index ETF matches, not beats, the index minus fees)
Watch out for
Assuming all ETFs are simple and low-risk. Synthetic ETFs, leveraged ETFs, and inverse ETFs carry significantly more complex risk profiles than a plain market-tracking ETF.
Buying an ETF without checking whether it is classified as an SIP at sips.abs.org.sg (opens in new tab). You may need to complete a Customer Account Review (CAR) before you can trade it.
Confusing an ETF’s traded price with its NAV. The two can diverge, particularly during periods of market stress.
Ignoring the tracking error disclosed in the fund factsheet. A consistently high tracking error suggests the ETF is not efficiently replicating its index.
Your next steps
Visit the SGX website (sgx.com (opens in new tab)) to browse the ETFs listed in Singapore. Note which are tagged ‘@’ (SIP) or ‘X@’ (synthetic SIP).
For any ETF you are considering, read its Product Highlights Sheet and latest factsheet — available from the fund manager’s website or on MAS OPERA.
Compare the Total Expense Ratio of the ETF to similar ETFs tracking the same index. Lower fees compound favourably over time.
If you are considering a synthetic ETF, read our article on synthetic ETFs first to fully understand the structure and risks involved.
For an overview on understanding ETFs
Frequently asked questions (FAQ)
What is an expense ratio and why does it matter?
The Total Expense Ratio (TER) is the annual cost of running a fund, expressed as a percentage of assets. It's deducted automatically from the fund's returns — you never see a bill, which makes it easy to ignore. But over 20–30 years, a TER difference of 1% per year can compound into tens of thousands of dollars of reduced wealth.
Can I buy ETFs without a brokerage account?
Some platforms offer ETF exposure without a traditional brokerage account — robo-advisors, for instance, typically invest in ETFs on your behalf. You can also invest in ETF-based Regular Savings Plans through some banks. However, to buy individual ETFs directly on the Singapore Exchange, you do need a brokerage account.
What is the minimum investment for a unit trust or ETF?
Unit trusts typically require a minimum lump-sum investment of $1,000, or $100–$500 per month via a Regular Savings Plan. ETFs are purchased in lots, so the minimum is one lot of the ETF's current market price. ETF RSPs through some brokerages start from $100/month.
Can I invest in ETFs through my Supplementary Retirement Scheme (SRS) account?
Yes — SRS-eligible investments include Singapore-listed ETFs, and many brokerages allow you to link your SRS account to trade on the SGX. This is a tax-efficient way to build a long-term investment portfolio.
Related articles
Guide to ETFs: How synthetic ETFs work
Synthetic ETFs deliver index returns through derivatives, not actual holdings—and that creates risks. Understand counterparty risk and collateral arrangements before investing.
Understanding unit trusts
Unit trusts let you invest in hundreds of assets at once—but fees can quietly eat away at returns. Understand NAV pricing, fund costs, and risks before investing in Singapore.
Managing investment risk
Higher returns always come with higher risk—but which risks are you actually taking? Understand market, credit, liquidity, and currency risk before building your Singapore portfolio.